A roof claim can feel uncertain long before an adjuster arrives. This insurance adjuster meeting case study shows how careful preparation helped a North Texas homeowner ask better questions, document visible damage, and move forward with less stress after a hailstorm.
The situation is representative of many homes we inspect around Mansfield, Midlothian, Waxahachie, and nearby communities. It is not a promise of any claim result. Every roof, policy, carrier, and adjuster assessment is different.
The Storm Damage Situation
The homeowner had lived in the same home for over 15 years. The roof was aging but had not leaked. After a spring storm, they noticed loose granules near downspouts. They also found small dents on metal vents and gutters.
The damage was easy to overlook from the ground. That is common after North Texas hailstorms. A roof can look mostly normal while shingles have lost protective granules or suffered bruising.
The homeowner contacted a local roofing contractor for an inspection before filing a claim. The inspection found signs consistent with hail impact on several roof slopes. There was also wind-related lifting along a few shingle edges.
The contractor explained the findings in plain language. They photographed the roof, metal components, valleys, flashing, and visible interior areas. The homeowner received a written estimate and a clear record of observed conditions.
That record did not determine coverage. It gave the homeowner organized information for their conversation with the insurance carrier.
Preparing for the Adjuster Meeting
The homeowner filed a claim directly with their insurance carrier. Once the carrier scheduled an inspection, the homeowner asked the roofing contractor to attend.
A contractor can be helpful at this meeting. They can point out areas that may be difficult to see. They can also explain roofing materials, installation details, and repair concerns. The adjuster makes the carrier’s assessment, while the contractor provides a professional construction perspective.
Before the meeting, the homeowner gathered the storm date, claim number, inspection photos, repair history, and the contractor’s written estimate. They also wrote down questions. This small step kept the discussion focused.
The preparation centered on four practical points:
- Visible hail impacts on shingles and metal roof components
- Wind-lifted or creased shingles near roof edges
- The roof’s age, condition, and matching materials
- Whether proposed repairs would address affected areas properly
The contractor also checked for active leaks. None were present at that time. Still, the homeowner was advised to watch ceilings, attic spaces, and wall areas after future rain.
What Happened During the Inspection
The adjuster arrived as scheduled and inspected the roof. The homeowner stayed nearby but let the professionals work. The contractor and adjuster discussed the visible conditions without turning the appointment into an argument.
That approach matters. A productive meeting is factual, calm, and specific. It is not about pressuring anyone for a certain answer.
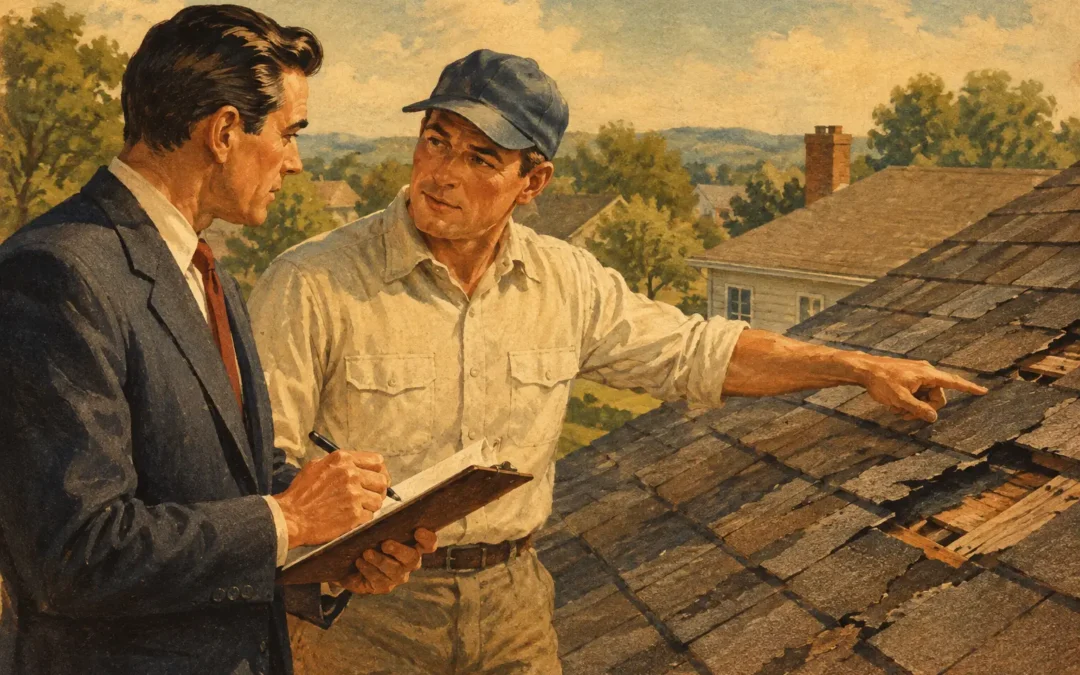
The contractor showed the adjuster photographed impacts on several slopes. They also pointed out matching marks on vents and gutter components. Those metal components helped establish that the storm had affected the property, not just one isolated shingle.
The adjuster measured roof sections and reviewed the shingle type. They inspected valleys, ridges, flashing, and roof penetrations. The contractor explained why a limited repair could be difficult if shingles were brittle, discontinued, or damaged across multiple areas.
This is where experience can make a difference. Roof damage is not always obvious. Hail strikes can leave subtle marks. Wind damage can appear as creases that may later affect shingle performance. An established local roofer knows where to look after the storms common in Ellis, Johnson, southern Tarrant, and southern Dallas counties.
The homeowner asked two useful questions: Which roof areas were included in the assessment, and what repairs were being considered? The adjuster explained that the carrier would review the inspection and send written claim information.
No one promised a result at the meeting. That honesty helped set reasonable expectations.
The Claim Review and Scope Differences
The initial claim paperwork included repairs to selected roof areas and replacement of some damaged accessories. The contractor reviewed the scope with the homeowner line by line.
There was a difference between the carrier’s initial repair approach and the contractor’s estimate. The difference involved labor, roof components, and the practical challenge of integrating repairs with existing materials.
Rather than telling the homeowner to accept or reject anything immediately, the contractor documented the questions. Additional photos and a detailed estimate were provided through the appropriate claim process. The homeowner remained in control of all communication with their carrier.
This is an important part of the case study. A scope of work is not always the final word. If a homeowner or contractor finds overlooked damage, missing components, or a construction concern, it may be appropriate to request a review. The carrier decides whether changes are warranted.
The homeowner also learned to compare scopes carefully. A lower number may reflect fewer items, not necessarily a complete repair plan. Roof decking, underlayment, flashing, ventilation, drip edge, and cleanup can all matter. The needed work depends on the home’s design and what is found during construction.
Local requirements matter too. Building standards can vary by municipality. A qualified contractor should account for applicable local requirements and notify the homeowner if concealed conditions appear after old materials are removed.
Lessons From This Insurance Adjuster Meeting Case Study
The strongest outcome was not simply a better-organized claim. It was a homeowner who understood the process and could make decisions with confidence.
First, schedule a professional inspection after a significant hail or wind event. Do not wait for a stain on the ceiling. Early documentation can be useful, especially when storm damage is subtle.
Second, keep the adjuster meeting factual. Bring photos, estimates, and questions. Let the adjuster inspect the property. A good contractor will communicate clearly without making unrealistic promises.
Third, review every document before work begins. Ask what each line item covers. Ask whether debris removal, permit needs, ventilation work, and material choices are included. Clear answers prevent surprises later.
Fourth, choose a contractor with local roots and direct accountability. Storm chasers often appear quickly after major weather events. They may not be available months later if questions arise. A long-standing local company has a reputation to protect in the same communities it serves.
Finally, understand that the insurance process has limits. Coverage depends on your policy and the carrier’s evaluation. A contractor should never promise a free roof, offer to waive a deductible, or guarantee a payout. Honest guidance is more valuable than a sales pitch.
A Better Way to Approach a Roof Claim
For this homeowner, the adjuster meeting became less intimidating because they were prepared. They had a documented inspection, a contractor who could explain roof conditions, and enough information to ask informed questions.
That is the real goal after a storm. You deserve a roof assessment that is thorough, a work scope that is clear, and a contractor who will still answer the phone after the job is complete.
Accent Roofing has served North Texas with honesty and integrity since 1980. If your roof has been through hail, wind, or years of Texas heat, a straightforward inspection can help you understand its condition and your next practical step.